

 Find a book


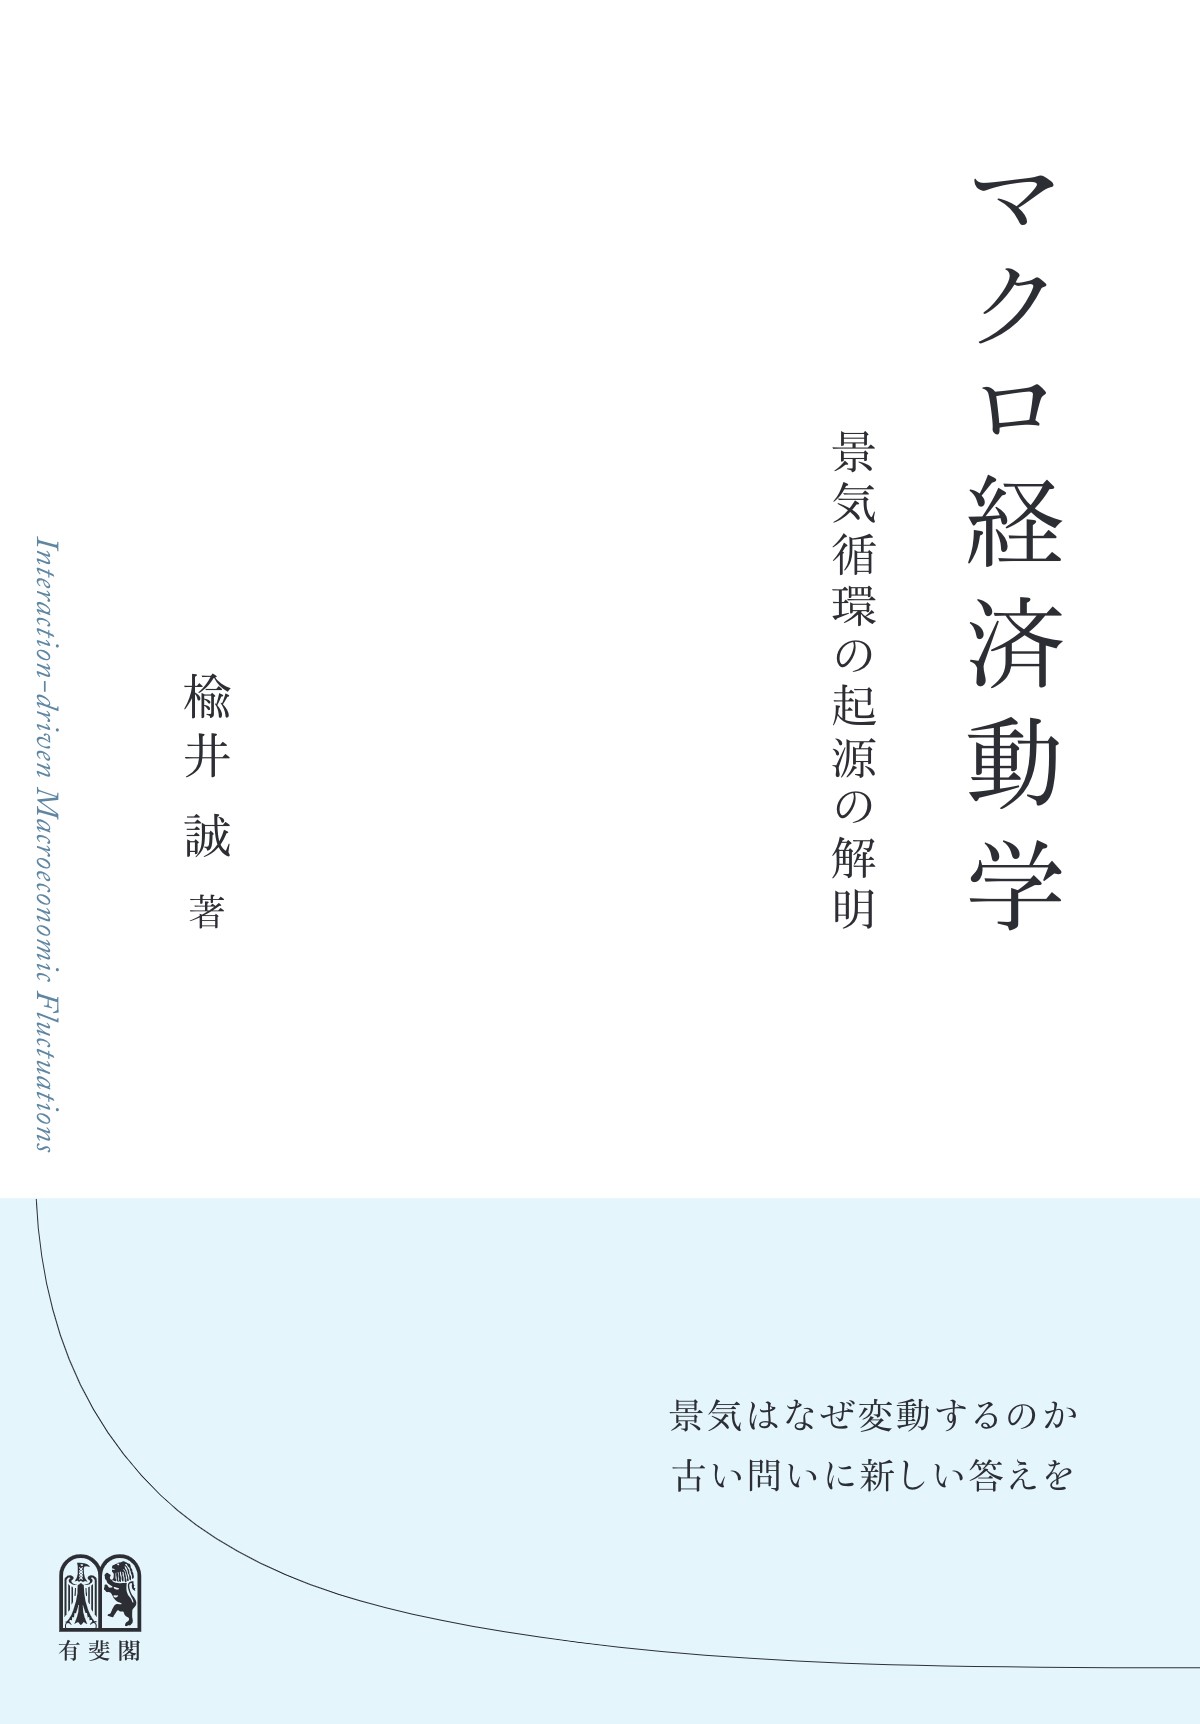
Title
Macro Keizai Dōgaku (Interaction-driven Macroeconomic Fluctuations)
Size
250 pages, A5 format, softcover
Language
Japanese
Released
November 21, 2023
ISBN
9784641166219
Published by
YUHIKAKU Publishing Co., Ltd.
Book Info
See Book Availability at Library
Japanese Page
 eBook
This book examines the conditions under which macroeconomic fluctuations emerge in the absence of clear external causes. The first part introduces a dynamic general equilibrium model, which serves as the standard framework in modern macroeconomics. The second part presents the theory of endogenous aggregate fluctuations. It explains my previous research, published in economics journals [1,2,3], for general readers interested in macroeconomic research and policy. A lecture article summarizing this research is also available in English [4].
To explain volatile markets, I apply the methodology of critical phenomena to a standard economic equilibrium model. A critical phenomenon occurs at the boundary between stable phases and is characterized by the synchronization of micro-level behavior. Synchronization is widely observed in nature and society: molecules in boiling water simultaneously transition into the vapor phase, fireflies gathered in a tree flash in synchrony, and traffic jams emerge randomly yet exhibit a recognizable regularity in the occurrence of rare but extremely long delays.
The central question of this book is as follows: Under what economic conditions does criticality arise? I focus on the complementarity and discreteness of micro-level economic actions. When complementarity is perfect—that is, when one action induces another on average—aggregate actions deviate from the central limit theorem regime and produce a fat-tailed distribution characterized by frequent “black swan” events. The book identifies three major macroeconomic variables that satisfy this condition: aggregate investment, short-run inflation rates, and high-frequency asset prices.
The criticality condition is derived from economic principles. With respect to aggregate investment fluctuations, a key observation is that production technologies in modern manufacturing are duplicable and indivisible. This characteristic implies discrete investment choices and globally constant returns to scale, under which a standard model of aggregate demand externality predicts that firms’ lumpy investments become perfect complements. In the context of inflation, the pricing behavior of monopolistic firms under menu-cost friction exhibits complementarity. When the long-run inflation rate is sufficiently high, the stationary density of firms located at the extensive margin increases, such that one firm’s repricing induces another firm’s repricing on average, leading to repricing avalanches that cause short-run fluctuations in the inflation rate. Finally, informed traders in asset markets infer the underlying value of assets from the transactions of other informed traders. This inference generates a game resembling Keynes’s beauty contest, in which traders are incentivized to follow the average signal revealed to the market through the actions of other traders. The model produces fat-tailed distributions of equilibrium asset prices and volumes consistent with those observed empirically.
Identifying the source of aggregate fluctuations is important because doing so determines whether policy intervention should counteract the shock. When aggregate fluctuations are driven by exogenous shocks to fundamentals such as technology, preferences, or endowments, these shocks do not necessarily cause inefficiency. Because competitive markets facilitate efficient reallocations, business cycles driven by such shocks represent efficient responses unless the economy is characterized by imperfect competition or incomplete markets. By contrast, the endogenous fluctuations demonstrated in this book lead to inefficient allocations of resources. For example, if investors could coordinate firms’ lumpy investments, they would choose a smoother consumption path for representative households by limiting firms’ extensive-margin investment adjustments. Endogenously generated fluctuations call for policies that alleviate market coordination failures.
References
[1] Nirei, M. (2015). An interaction-based foundation of aggregate investment fluctuations. Theoretical Economics, 10:953--985.
[2] Nirei, M. and Scheinkman, J.A. (2024). Repricing avalanches. Journal of Political Economy, 132:1327--1388.
[3] Nirei, M., Stachurski, J., and Watanabe, T. (2020). Trade clustering and power laws in financial markets. Theoretical Economics, 15:1365--1398.
[4] Nirei, M. Interaction-driven macroeconomic fluctuations. Japanese Economic Review, forthcoming.
(Written by NIREI Makoto, Professor, Graduate School of Economics / 2026)
Related Info
The 67th Nikkei Economic Books Cultural Award 2024 (Grand Prix) (Japan Center for Economic Research 2024)
https://www.jcer.or.jp/en